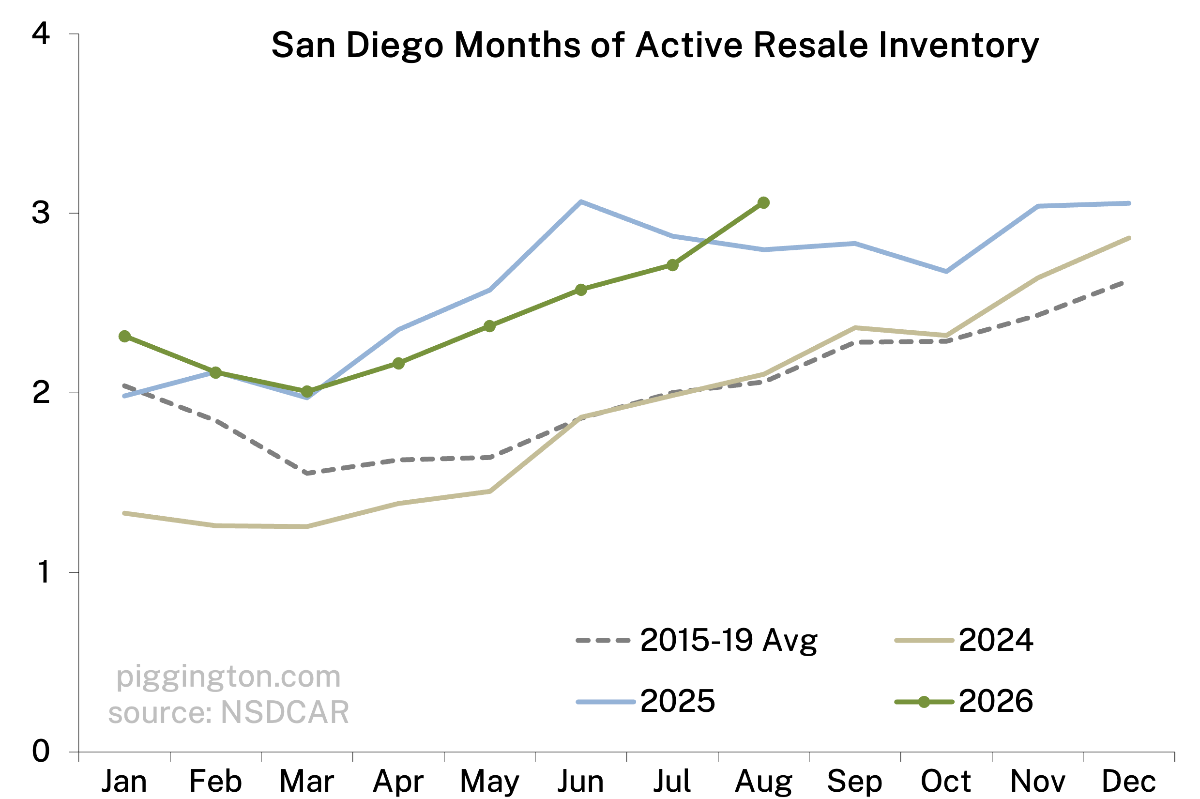
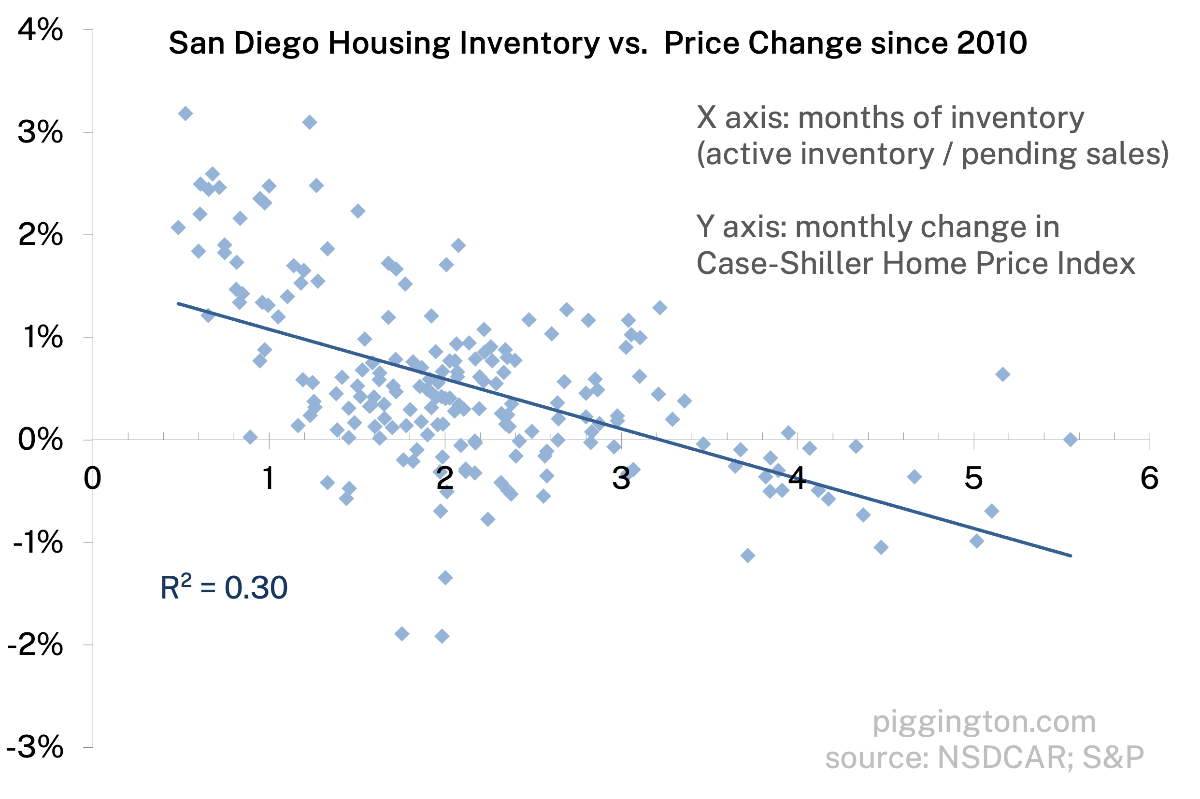
Hello. Months of inventory has risen to tie its 2025 high point (achieved during the tariff panic). This points to more slog ahead, and perhaps some further shambling towards affordability.
More graphs below…
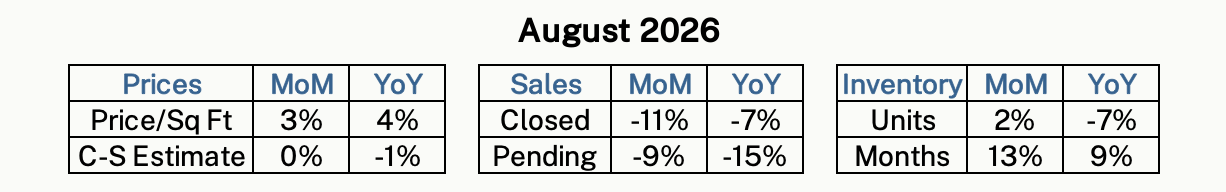


Hello. Months of inventory has risen to tie its 2025 high point (achieved during the tariff panic). This points to more slog ahead, and perhaps some further shambling towards affordability.
More graphs below…
Mortgage rate are approaching 7% again… New normal? Prices will have to adjust at some point
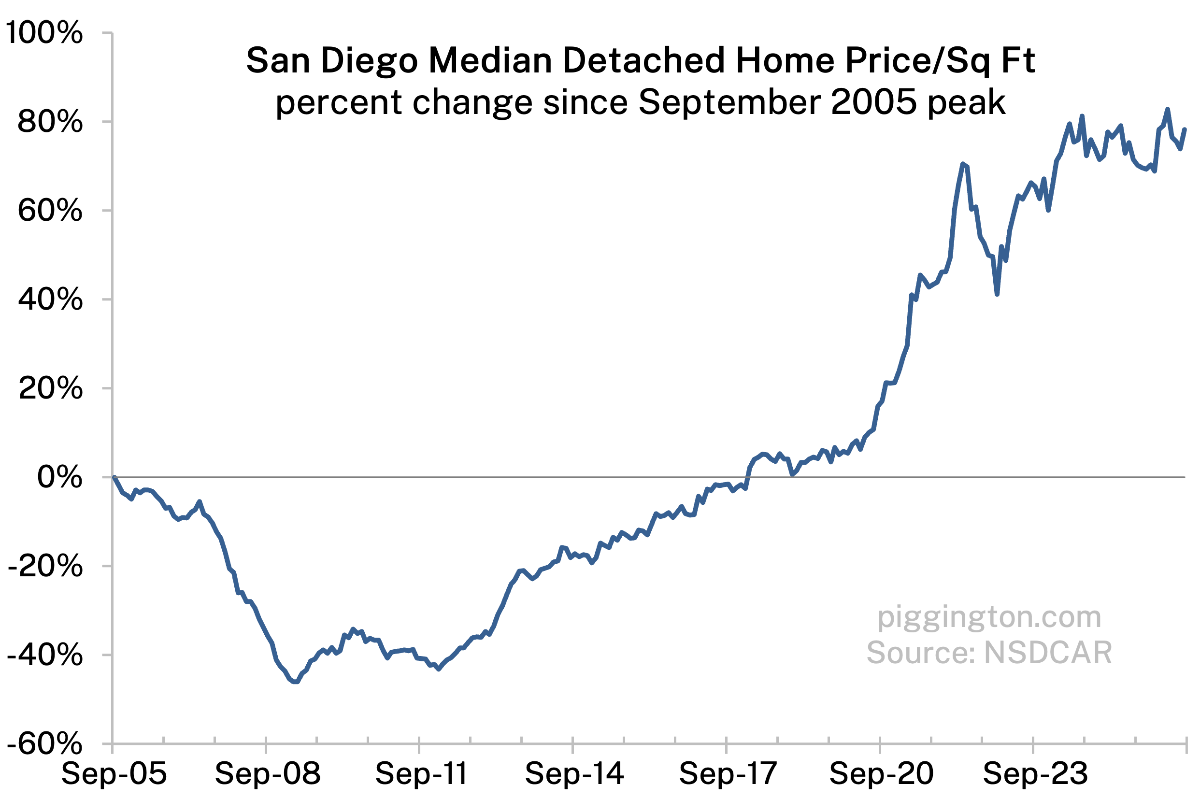
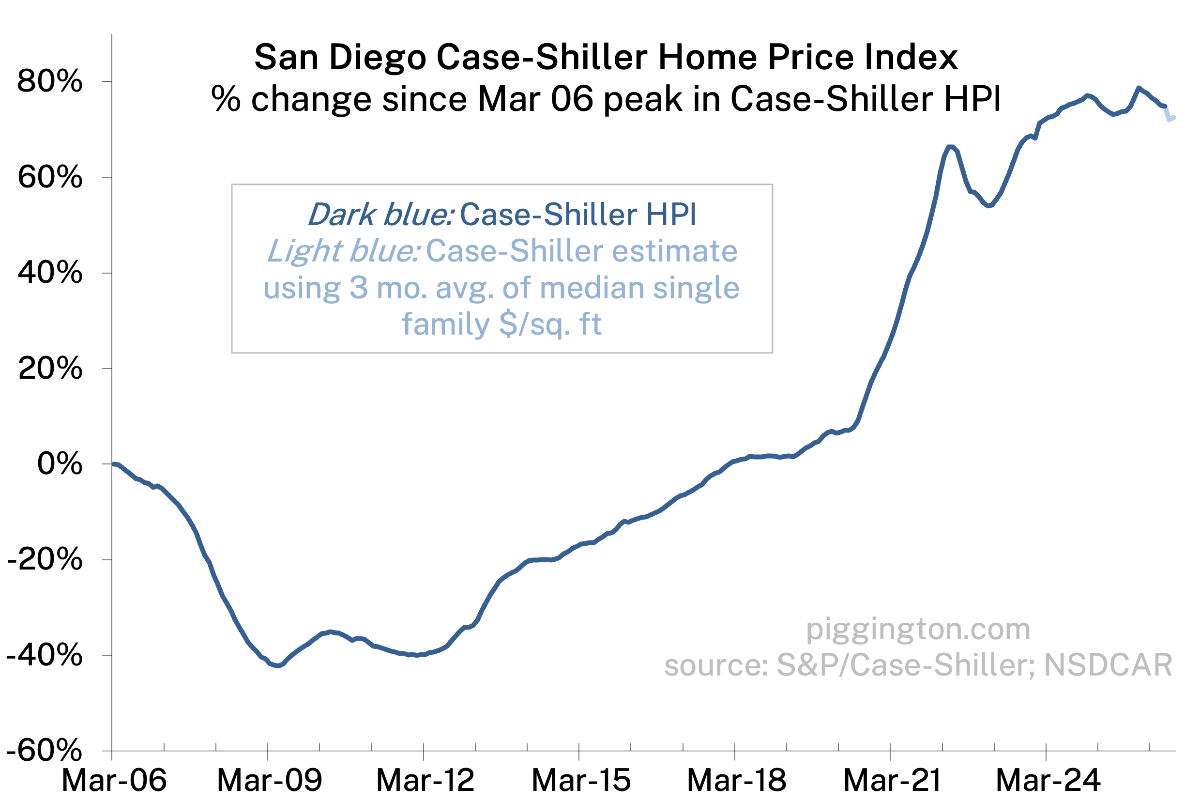
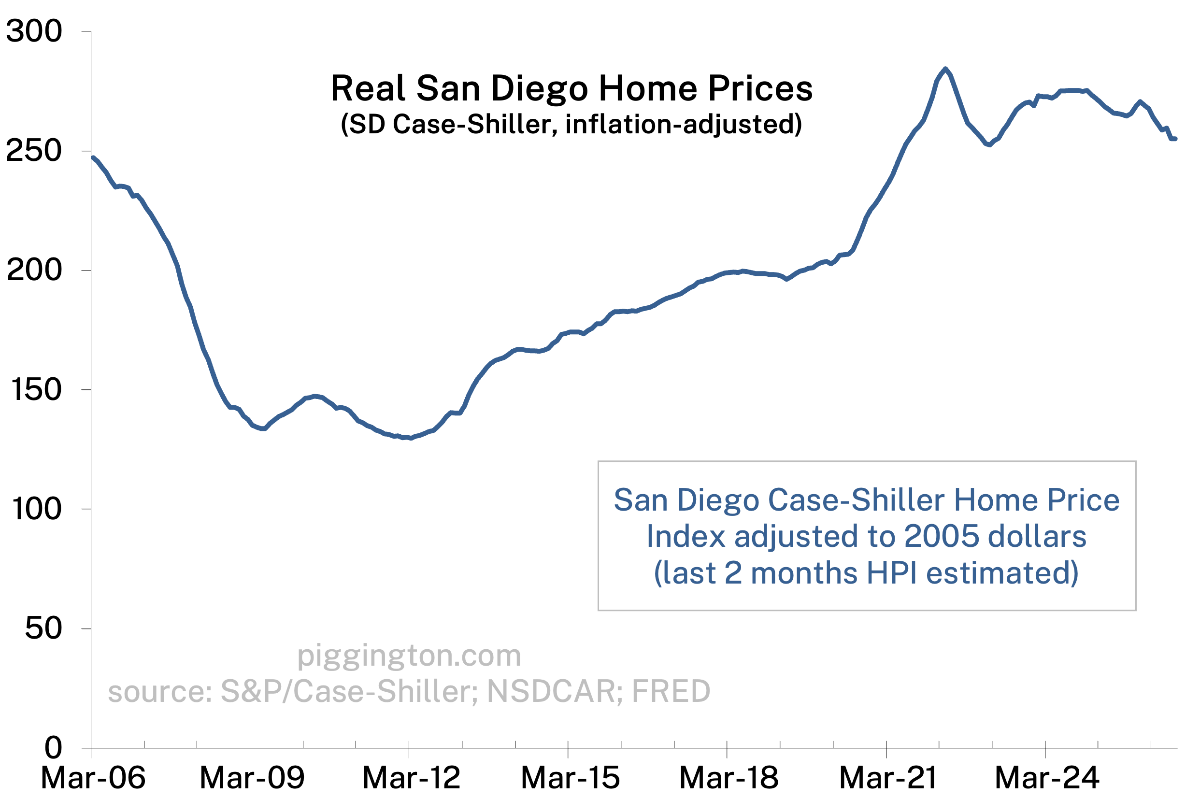
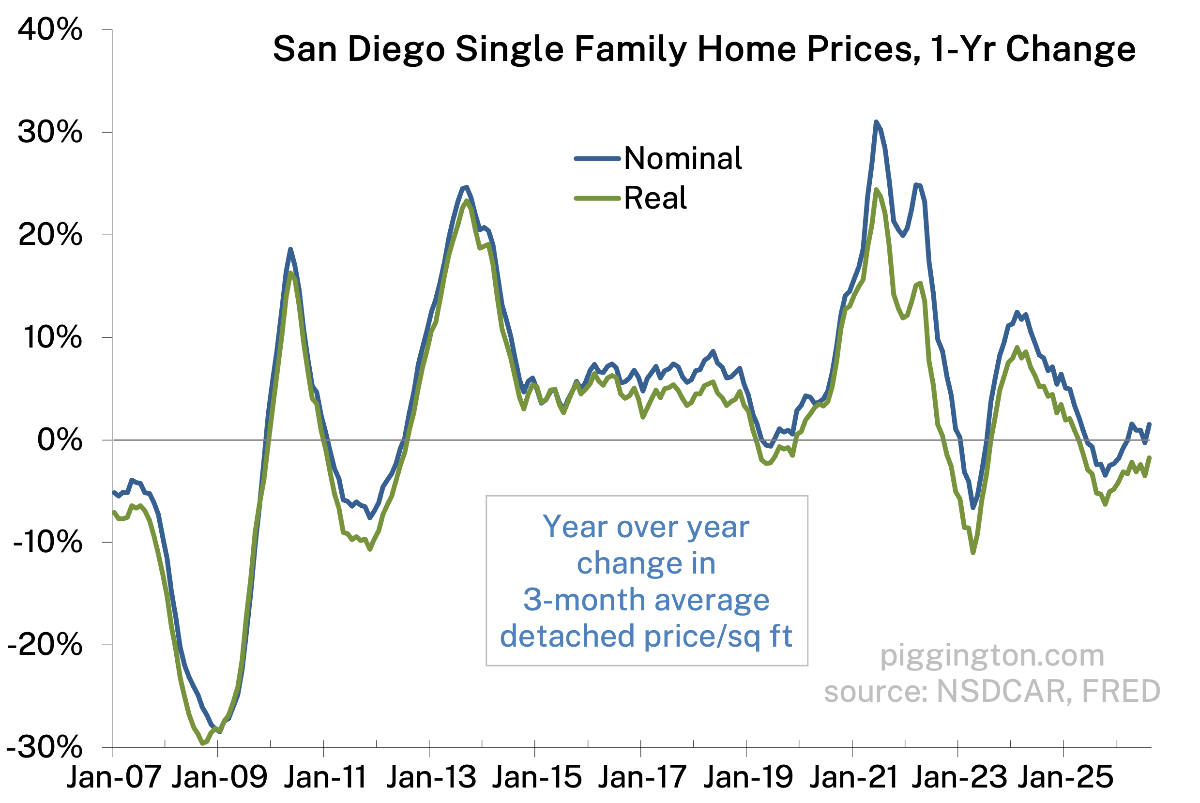
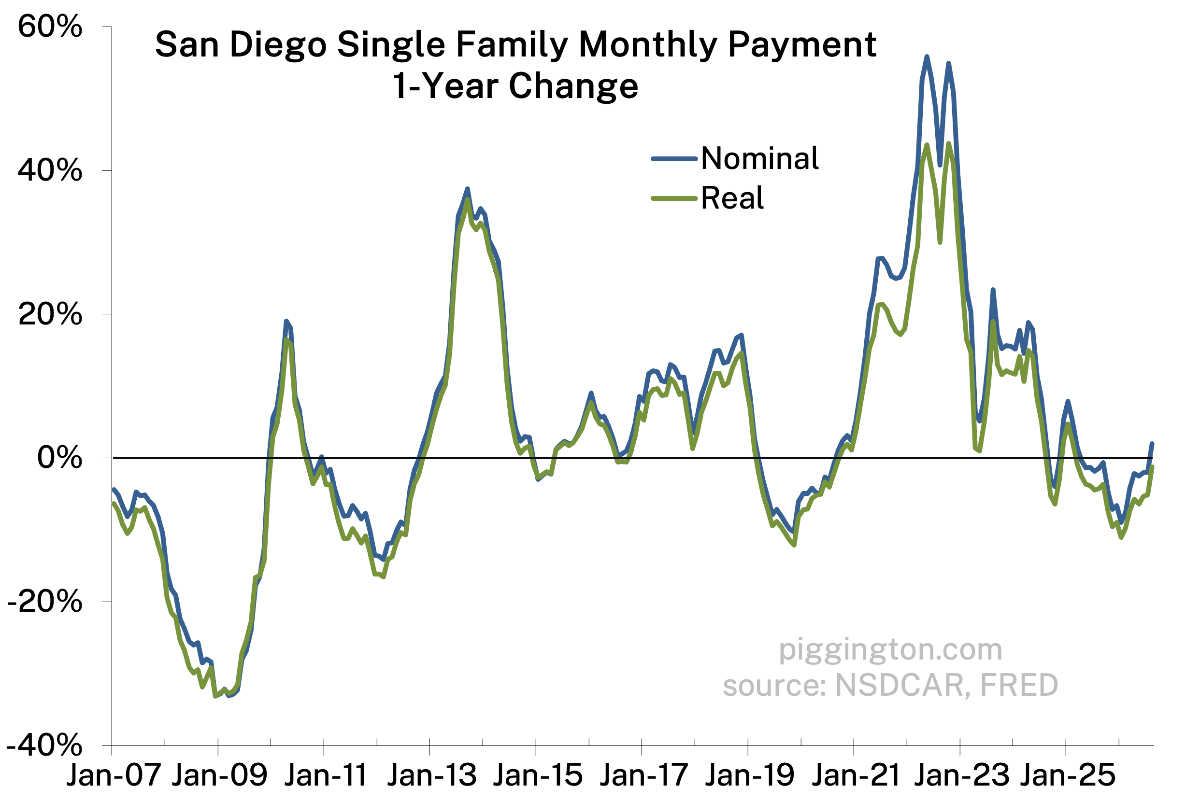
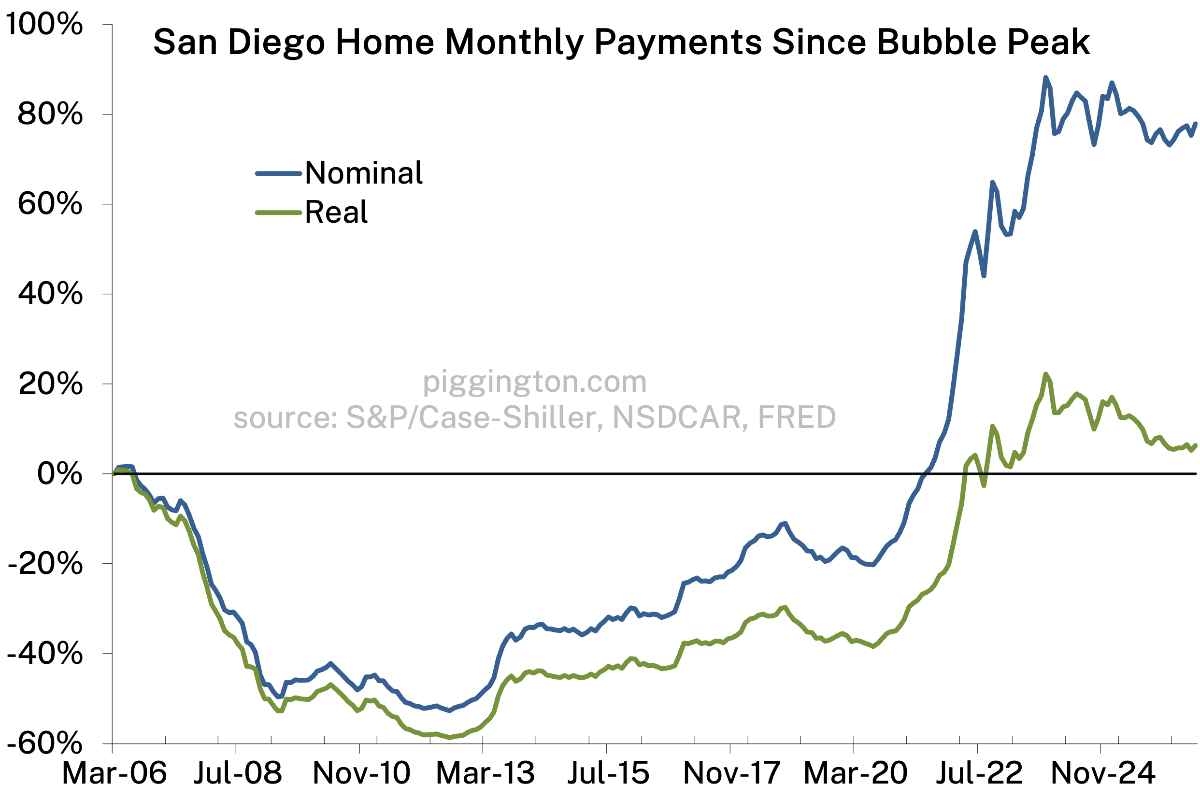
They have adjusted somewhat in real terms, which I think is the most meaningful way to look at it. Down 10% since the spring 2022 peak. But I agree with you that there is likely more to go. They haven’t adjusted enough to reflect the new rate climate, as the recent affordability graphs show: https://piggington.com/shambling-towards-affordability-june-2026/
This is totally just be postulating, but I think that people that are buying still are getting mortgages that will put them in a very tough spot if we enter a recession or ai starts increasing unemployment. The FED is raising rates which usually leads to a recession so this is something to consider… I think a lot of people will be forced to sell if they’re stuck holding an 8k mortgage over a period of unemployment.
Also still me postulating, but also know multiple people who did this, I think a lot of people who bought over the last few years were assuming mortgage rates will drop and they could refinance, so bit off more than they can chew. The whole “date the rate” thing really misled people
Assuming inflation keeps running around 3.5%, wages growing at a slightly slower pace, and 30 year mortgage rates in at 7%-ish for the foreseeable future. IMO, not a lot of upside in this market… Feels like we are entering a cold freeze as far as prices going up barring a significant stimuli. Most of the major possible inputs would probably push us to the downside (Prop 13 refactoring, trade war, gov’t cutbacks, etc)… The affordable housing apartments that are going up likely to put downward pressure on the market, and should keep rents down even if more folks move here (including remote workers). Right now the gap between monthly rent and monthly mortgage payment is quite large in higher end communities.
The government is our biggest employer but local/county revenues are not going up without significant private sector expansion. Sometimes it seems like we are a county of government pensioners… I have heard that the VA, CalPers etc are actually fighting back now and taking people pensions away who have abused the system. Have heard anecdotes and saw this article recrently:
https://calmatters.org/politics/2026/09/calpers-clawback-lawsuit/
Personally had a deck of a time getting any kind of unemployment from teh state in 2023-2024… I wonder if this crackdown on government benefits happens at scale, it might have downstream effects on things like San Diego real estate market.
On upside, there was talk about that big biotech thing downtown but seems to have fizzled out some (Marcus Lemonis etc?). San Diego needs significant job producers and investment in private sector to drive RE prices up further from where they are at now. This is what happened in 2021-2022 when so many CA tech workers who went remote moved here… More jobs locally would also help bring in more tax revenue. More low quality housing with big tax breaks for developers… Not so much.
Thanks for sharing the data. 🙂